-black.png)
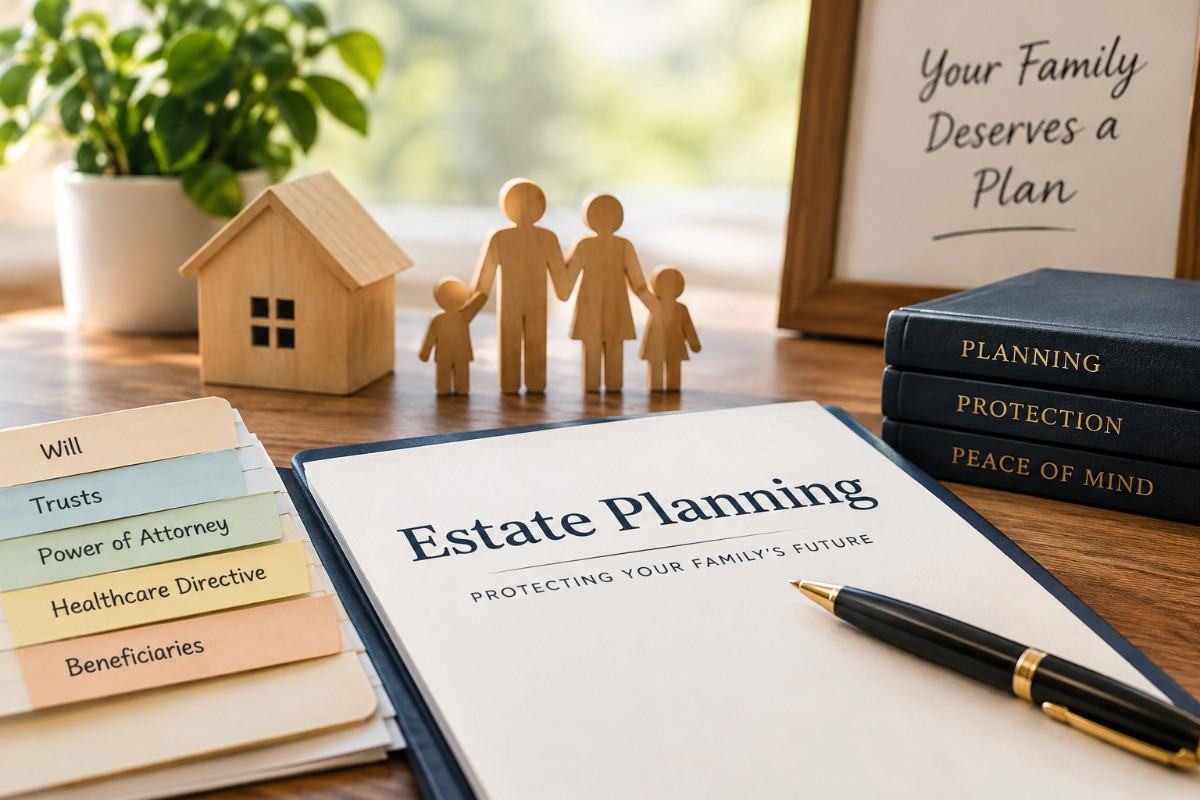
Three hundred dollars. That's roughly what it costs to file a deed correction in Florida after someone dies without a properly funded trust. That same three hundred dollars, spent on getting the paperwork right the first time, is the difference between your family grieving in peace and your family grieving inside a courthouse. I've watched the second scenario play out more times than I'd like, and it almost never starts with a dramatic mistake. It starts with a binder nobody updated.
You don't need a law degree to understand what estate planning actually does. You need about ten minutes and a willingness to look at the unglamorous parts: titles, beneficiary boxes, signatures, dates. That's the whole game. So here's what I'm going to do. I'll walk you through how these documents work in plain terms, point out the spots where families quietly go wrong, and give you a checklist you can act on this weekend. No jargon. No scare tactics. Just the mechanics.
What Estate Planning Actually Does (Hint: It's Not About You)
Most people assume estate planning is about controlling what happens to your stuff after you die. That's part of it. The bigger part is about removing decisions from your family's plate during the worst two weeks of their lives. A will says who gets what. A trust holds assets so they skip probate. A power of attorney names someone to handle your money if you can't. A healthcare directive tells doctors what you want when you can't speak. Each one solves a specific, narrow problem. None of them does everything.
Here's the part that trips people up: signing the document isn't the finish line. A will sitting in a drawer while your house is titled in your name alone doesn't avoid probate. A trust that never got funded is just an expensive piece of paper. You have to move the assets into the structure you built, and that step is where most DIY plans fall apart.
I'd rather you walk into an initial consultation knowing that than walk in expecting a single document to fix everything. Set your expectations low on magic and high on follow-through.
Why the Setup Usually Outperforms the Emergency
There's a pattern I keep seeing. Someone calls in a panic because a parent died, the bank account is frozen, and nobody knows who's supposed to pay the mortgage. The parent had good intentions. They just never finished the administrative half of the plan. The emergency version of estate planning costs more, takes longer, and creates family arguments that never fully heal. The setup version, done quietly on a Tuesday afternoon, costs a fraction of that and mostly involves signing things.
According to the Federal Trade Commission, scammers frequently target older adults precisely because financial decision-making gets harder with age and because family members often don't have clear legal authority to intervene. A signed power of attorney closes that door. An unsigned one doesn't exist. Think about which version you'd rather hand your kids.
How to Pick the Right Help Without Overpaying
Not every situation needs the same level of firepower. A single person with one bank account and no property has a very different problem than a couple with a house, a business, and three kids from two marriages. Match the tool to the job.
- Simple will only: modest assets, no real estate outside your name, clear family structure.
- Will plus trust: property, a business interest, or a desire to keep things out of probate court.
- Full package with directives: anyone over 60, anyone with a complicated family tree, anyone who wants a say in medical decisions.
- Business succession layer: anyone who owns part of a company, even a small one.
When you're comparing providers, ask two questions. First, who actually drafts the documents, a paralegal or the attorney whose name is on the door? Second, what happens after signing: do they help you retitle accounts, or do they hand you a folder and wish you luck? The second question matters more than the first. Someone searching for an attorney for estate planning davie residents can trust should expect both document drafting and the follow-through that makes those documents functional. A firm that only does half the job is cheaper up front and far more expensive later.
The Boring Steps That Decide Everything
This is where the real work lives, and it's the part most articles skip because it isn't interesting. I'm including it anyway, because it's the difference between a plan that works and a plan that looks good in a folder.
1. Retitle the accounts. If the trust is supposed to own the house, the deed needs to say so. Check every account, every property, every vehicle title.
2. Update beneficiaries. Retirement accounts and life insurance pass by beneficiary designation, not by will. An old form from a previous marriage overrides your shiny new will every single time.
3. Name backups for your backups. One executor and one alternate is a coin flip. Name two alternates if you can.
4. Sign it correctly. Florida has specific witnessing and notarization requirements. A document signed wrong is a document that doesn't count.
5. Store it where someone can find it. A safe deposit box your executor can't access is a safe deposit box that doesn't exist.
6. Tell one person the plan exists. You don't have to share details. You do have to tell your executor where to look.
My honest take on this list: items two and five cause more family heartbreak than everything else combined. I've seen siblings stop speaking over a beneficiary form nobody remembered signing in 2011.
What Changes Over Time (And Why You Have to Revisit It)
Estate plans have a shelf life. Marriages, divorces, births, deaths, a big jump in income, a move to another state, a business sale. Any one of those can quietly invalidate a plan you paid good money for. According to the Federal Deposit Insurance Corporation, deposit insurance covers accounts up to a set limit per depositor, per institution, and the way accounts are structured affects who gets protected. That's a technical detail, but it illustrates something bigger: ownership structure has consequences, and those consequences shift as your life changes.
A practical rule I'd give anyone: reread your plan every three years, or after any major life event, whichever comes first. Put a calendar reminder in your phone right now. It takes thirty seconds and it's the single highest-return thing you can do today.
A Real Scenario, Straight From the Messy Middle
Suppose it's a Thursday night. Your father has a stroke. He's alive, he's conscious sometimes, and he can't sign anything. The mortgage is due in twelve days. His bank account is in his name only. If he signed a durable power of attorney two years ago, one phone call and your name is on the account. You pay the mortgage. You keep the lights on. You focus on him.
If he didn't, you're filing for emergency guardianship, which means a court date, a lawyer you didn't plan to hire, and a timeline you don't control. The medical crisis is bad. The legal freefall on top of it is what actually breaks families. That's the whole argument for boring paperwork. It's not about death. It's about the Thursday night when everything goes sideways and you need someone to already have authority to help.
The Paper Trail Test: A Simple Way to Judge Your Own Plan
Here's a framework I use when I review a plan that's already been signed. I call it the paper trail test. Ask yourself three questions about every major asset you own. Who is legally entitled to it today? What document proves that? And could a stranger find that document in under ten minutes?
If you can answer all three for your house, your accounts, and your car, you're in better shape than most people. If you can't answer even one, that's your homework. Wills and trusts get the attention, but the paper trail is what actually moves money. According to the Internal Revenue Service, assets passing at death have specific reporting requirements, and errors in how ownership was structured often surface years later during estate filings. Keeping clean records from the start saves your family an audit headache they never asked for.
Start With One Folder
You don't have to solve this in a weekend. Get a folder, physical or digital, and start dropping in what you have: account statements, deed copies, beneficiary designations, any old will. That single act puts you ahead of most families in America. Then make one call. Not five. One. Ask whether your current documents still do what you think they do. If you want a starting point, search for an attorney for estate planning davie and read the reviews before you book anything.
Because the question isn't whether your family will need this paperwork. It's whether they'll find it finished or find it started.