-black.png)
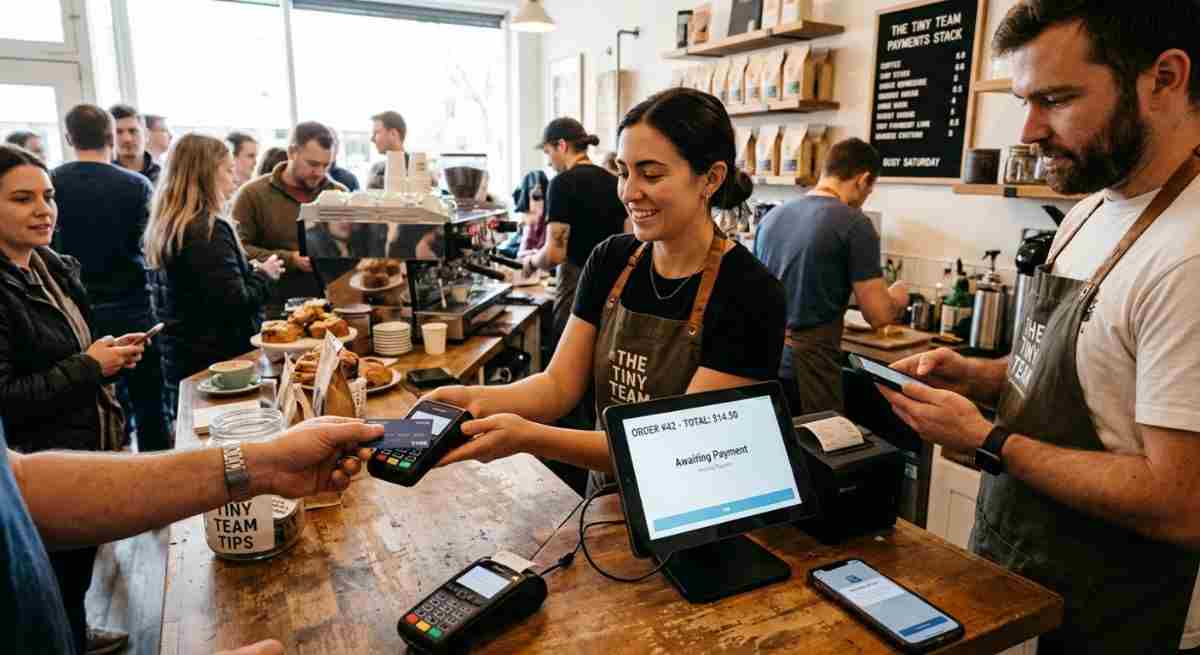
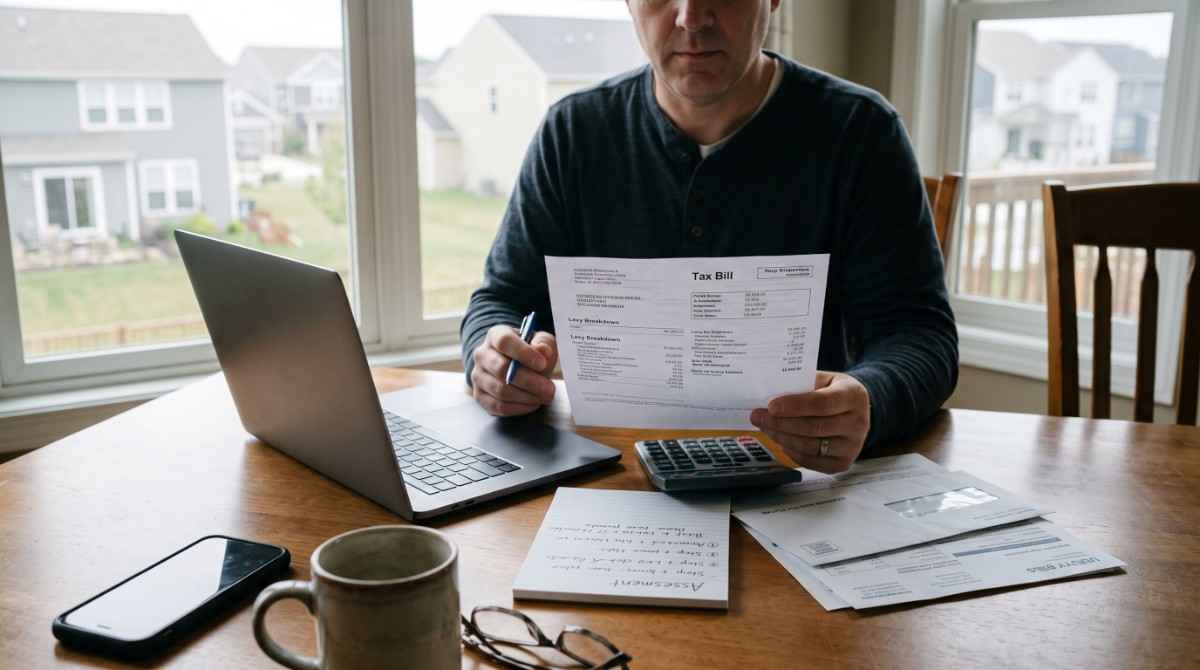
Two people. One phone. A card reader that keeps dropping its Bluetooth pairing in the middle of a rush. That is the real payments department at most small businesses, and nobody is coming to staff it for you. So the stack has to be built around your actual hands, not a fantasy org chart. Every extra app you add is another login somebody has to remember, another place a payment can silently fail. I have watched a three person coffee roaster burn an entire afternoon reconciling payouts across four different tools, and none of that work made a customer happier.
Pick fewer things. Make each one earn its spot. And when you go shopping, look for merchant services for small business built for a one screen workflow instead of a corporate finance department. Below is the stack I would assemble if I were a solo operator or a shop with a handful of people, plus the order I would add pieces as you grow.
The Two Rules That Kill Bad Payment Setups
Rule one: every payment method you accept has to end up in the same place. Card taps, cash, invoices, a bank transfer for the client who insists on paying by ACH, all of it should land in one view you can read in under a minute. If your card processor and your invoicing app each keep their own tiny kingdom, you will spend your slow mornings as an unpaid accountant.
Rule two: someone has to be able to take a payment when you are not standing there. That might be a crew member with the app on their own phone, or a payment link you text to a customer at dinner. If the whole system lives on your personal phone and your personal face, you have built a bottleneck with your name on it. These sound obvious. Almost nobody does both. According to the Small Business Administration, the overwhelming majority of American firms have fewer than 20 employees, which means the "tiny team" is not an edge case. It is the default.
Three Layers, In This Order
Think of your setup as three layers. You only need to buy the layers you actually use today. Adding layers early is how people end up paying for features they cannot name.
-
Accept the money. A card reader or tap-to-pay on a phone for in-person sales, plus some way to take a payment remotely.
-
Record the money. One place where payments, customer names, and notes live together, ideally syncing to your bookkeeping.
-
Chase the money. Automated invoices and reminders for anything billed after the fact.
Most small shops skip straight to the flashy reader and ignore the middle layer entirely. That is backwards. The worst payments day of your month will almost always be a records problem, not a hardware problem.
What a Real Stack Looks Like for Four Very Different Shops
Text beats categories here, so here are four quick sketches. A plant nursery with a Saturday rush. One counter terminal, one tablet in the greenhouse for tap-to-pay, and a shared login so whoever is closest to the customer taps the card. No invoices. The owner reconciles Sunday morning in about ten minutes.
A mobile mechanic. Card reader in the truck for jobs in driveways, plus the ability to text a payment link when the customer is not on site. The mechanic never handles cash for parts deposits, which cuts out a specific kind of headache.
A wedding florist billing months ahead. Deposit invoice online, final balance invoice, and automated reminders so nobody has to be the person hounding a bride about an overdue balance. This is where the chasing layer earns its cost.
A two person tax office. Bank transfers for the clients who prefer them, card for walk-ins, and one report that gets exported before tax season rather than one quickly built spreadsheet.
Notice what is missing from all four. Nobody built a custom integration. Nobody hired a payments consultant. The most common setup mistake, by far, is overbuilding on day one and then abandoning half the tools.
Match Your Setup to How Your Customers Pay
Picture a cafe whose customers usually walk in and tap a card. Any modern reader handles that. Now picture a building contractor whose customers prefer to settle a large invoice by bank transfer, because they are the ones writing the check and they care about their own process. Data from the Census Bureau shows the retail and service economy is spread across a wide range of business sizes and customer profiles, which is why one universal stack does not exist.
So run the math on your own customer list. Sort your last fifty payments by method. If a third of them came in as checks or transfers, your stack needs a remote billing lane, not just a counter reader. If nearly all of them tap in person, spend your money on speed at the counter and skip the invoicing add-on for now. The failure I see most often is a shop buying a feature because a competitor has it. Somebody else's customer base is not your customer base. Their stack is not a template.
The Saturday Test
Here is the practical part. Before you commit to any setup, run what I call the Saturday Test. You simulate your busiest two hours and check three things.
One: Can a person who started this morning take a payment without calling you? Hand them the device and say nothing. If they stall, you have a training or permissions gap.
Two: If the internet drops, does the device keep working or does the line stop? This matters more than any feature list. Ask the provider point blank.
Three: When you look at yesterday's payments, can you tell in under a minute how much came in, by method, without opening three dashboards? If not, the records layer is broken.
Three questions, not thirty. The Saturday Test catches the failures that actually cost you money. Nobody cares whether your processor has a feature nobody on staff can find.
Red Flags Before You Sign Anything
The Consumer Financial Protection Bureau exists in part because financial products are complicated, and small business owners deserve clear terms up front. Contract length is the red flag I would check first. A long commitment with a big early termination fee locks you into a stack you might outgrow in a year.
Ask what happens if you want to add a second user. Ask where your payout schedule is written down. Ask how a dispute gets handled and whether anyone on staff has done one before. If the salesperson cannot answer the dispute question without pausing, that tells you something. I would rather pay a little more for a provider whose terms fit on one page than chase a slightly lower rate through a maze of conditions.
Adding Layers Without Adding Chaos
Growth does not mean you should bolt on every tool in the store. Start with the layer that hurts most, run it for a full month, and only then consider the next one. When you add something new, retire something old in the same week. Keeping both is how a tiny team drowns in tabs. The specific thing worth testing first: taking a payment from your phone while away from the counter. If you can send a link and get paid while loading a truck, you have found real time back. That tends to be the switch that makes a business owner say, out loud, that the stack finally works.
Your payments setup should be boring. Boring means it failed quietly and you fixed it once, on a Tuesday, instead of once a month at the register. Build the version that survives a busy Saturday with the people you actually have. If you have already run the Saturday Test on your current setup, what broke, and what did you swap in to fix it?