-black.png)
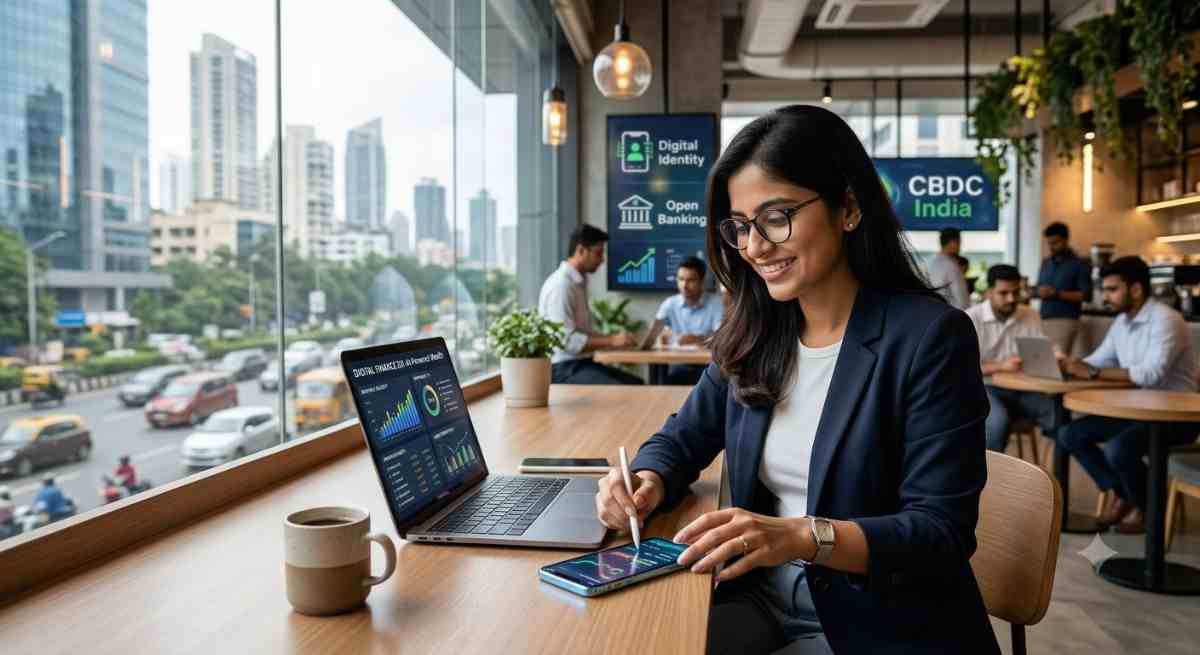
From instant transactions to intelligent money management, the next phase of digital finance is set to transform how people save, borrow, invest and interact with money.
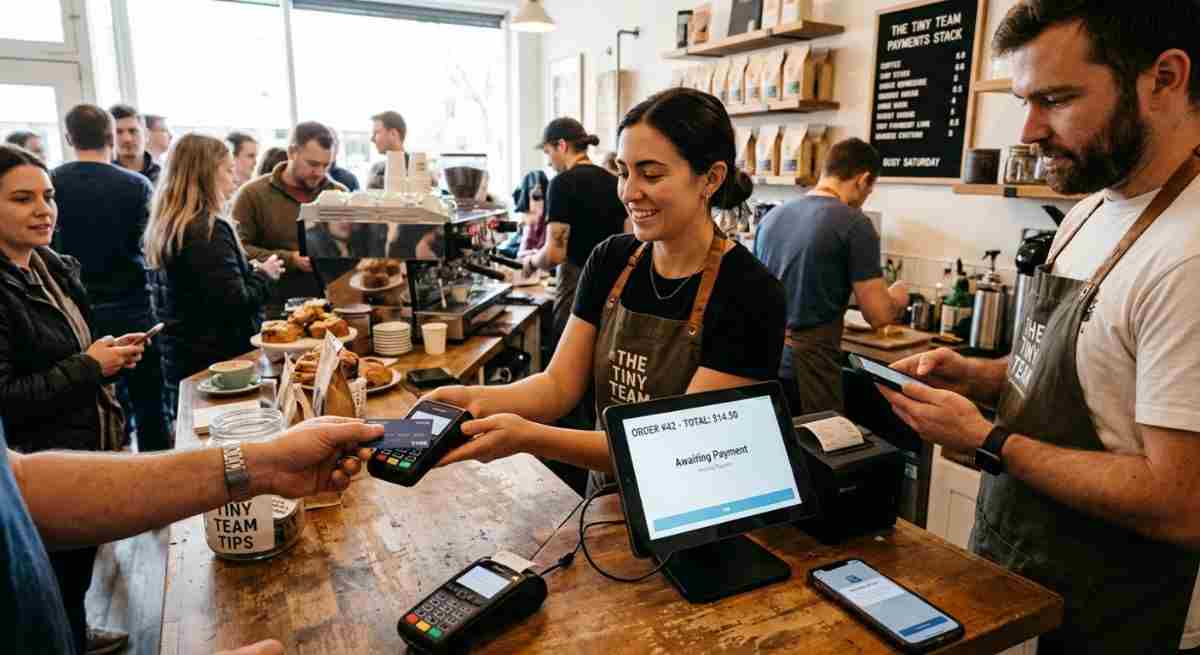
The way people manage money has changed dramatically over the past decade. From standing in long queues at banks to transferring money within seconds using a smartphone, digital payments have revolutionised everyday financial transactions. In India, the rapid adoption of Unified Payments Interface (UPI), mobile banking, digital wallets and QR-code payments has made cashless transactions a part of daily life.
However, the digital finance revolution is far from over. As mobile payments become increasingly mainstream, the financial sector is preparing for its next transformation: Digital Finance 2.0. This new phase is expected to move beyond simply transferring money and focus on making financial services smarter, more personalised, accessible and seamlessly integrated into everyday activities.
Beyond Payments: The Rise of Intelligent Finance
The first phase of digital finance focused primarily on convenience. Consumers could pay bills, transfer funds, shop online and access banking services without visiting a physical branch. Digital Finance 2.0 aims to take this convenience several steps further.
Artificial Intelligence (AI) and machine learning are expected to play a significant role in this transformation. Financial platforms are increasingly using intelligent systems to analyse spending habits, identify unusual transactions, provide personalised financial suggestions and help customers make informed decisions.
Imagine a banking application that does more than display your account balance. It could automatically categorise expenses, remind you about upcoming payments, suggest savings opportunities and help you plan monthly budgets. Such features could turn digital banking platforms into personal financial assistants.
Open Banking and Connected Financial Services
Another important development shaping the future of digital finance is open banking. It enables customers to securely share their financial information with authorised third-party service providers, subject to consent and applicable regulations.
This could create a more connected financial ecosystem where banking, insurance, investments, lending and financial planning work together.
In India, the Account Aggregator framework is an important step towards consent-based financial data sharing. It can help individuals and businesses access financial services more efficiently by allowing them to share verified financial information digitally.
For small businesses, freelancers and entrepreneurs, this could make accessing credit easier by helping lenders assess financial records and cash flows more effectively.
The Next Generation of Digital Lending
Traditional lending often involves extensive paperwork, lengthy verification processes and multiple visits to financial institutions. Digital Finance 2.0 is expected to make borrowing faster and more accessible.
With the help of digital documentation, alternative data assessment and automated verification, financial institutions can potentially evaluate loan applications more efficiently.
This development could benefit small entrepreneurs, women-led businesses, self-employed professionals and individuals who have limited access to conventional banking services.
However, faster lending must go hand in hand with responsible credit practices. Transparent interest rates, fair lending standards and customer awareness will remain essential.
Blockchain, Digital Identity and the Future of Transactions
Blockchain technology is another area attracting attention in financial innovation. Its potential applications include faster settlement systems, transparent record-keeping, digital asset management and smart contracts.
Meanwhile, digital identity solutions are helping make financial onboarding and verification more convenient. In India, Aadhaar-enabled services, digital KYC and UPI demonstrate how technology can simplify access to financial infrastructure.
Central Bank Digital Currencies (CBDCs) may also influence the future of money. India's Digital Rupee, launched as a pilot by the Reserve Bank of India, represents an important experiment in exploring digital currency issued by a central bank.
Security and Financial Inclusion Must Remain Priorities
As financial services become more interconnected, cybersecurity and data privacy will become increasingly important. Digital fraud, phishing attacks, identity theft and unauthorised access remain serious concerns.
Financial institutions must invest in stronger authentication, fraud detection systems, encryption and consumer education. Customers, too, need to remain cautious about sharing OTPs, passwords and confidential banking information.
Equally important is ensuring that digital finance does not leave anyone behind. Rural communities, senior citizens, small traders and people with limited digital literacy must be included in the transformation through accessible technology, regional-language support and financial education.
What Does the Future Hold?
Digital Finance 2.0 is not simply about replacing cash or making payments faster. It represents a broader shift towards an intelligent, connected and inclusive financial ecosystem.
In the coming years, financial services may become increasingly invisible, operating seamlessly within shopping platforms, business applications and everyday digital experiences. Consumers may spend less time managing transactions and more time making meaningful financial decisions.
The real success of this transformation will not be measured only by the number of digital payments made, but by how effectively technology improves financial security, independence and opportunity.
Mobile payments changed how we move money. Digital Finance 2.0 could change how we understand, manage and build our financial future.